Savviest Saver

We Compared the Top Home Equity Vendors and Found a Clear Winner

Tommy Barnes
By Tommy Barnes ◦ October 01, 2026

Here’s a scenario that’s become pretty common: you own a home, and whether your mortgage rate is fantastic or not so fantastic, your house is now worth a lot more than when you bought it. Maybe you’re staring down a kitchen remodel, a roof that needs replacing, or just a pile of higher-interest debt you’d like gone. On paper, you’re sitting on a pile of money. In real life, that money is locked inside your walls, and the only ways to get it out have historically been a home equity loan or a HELOC; both of which mean a new monthly payment and interest piling up, on top of whatever you’re already paying.

Over the last few years, a different option has shown up: the home equity investment, sometimes called a home equity agreement.

The Basic Idea

Instead of lending you money, a company essentially buys a small slice of your home’s future value. They hand you cash today. In exchange, when you sell, refinance, or the term ends, they get their money back plus a cut of however much your home went up in value.

You get a lump sum now. You owe nothing monthly. When the agreement ends, you pay back their original investment plus a share of your home’s appreciation (or, in rarer down-market cases, they can share in a loss too). That’s it, that’s the whole mechanism.

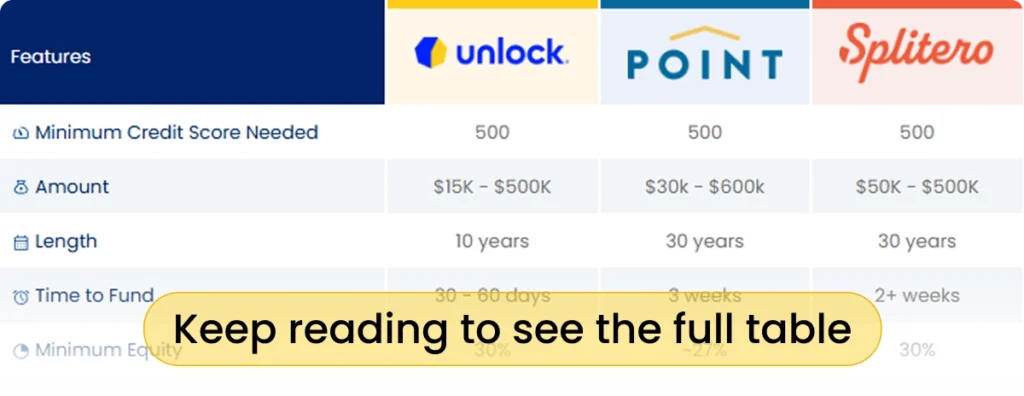
Two names keep coming up in this space: Unlock, Point and Splitero. They do roughly the same basic thing, but the differences between them actually matter quite a bit depending on your situation. Here’s the breakdown, without the sales pitch.

Features
Minimum Credit Score Needed
500
500
500
Amount
$15K - $500K
$30k - $600k
$50K - $500K
Length
10 years
30 years
30 years
Time to Fund
30 - 60 days
3 weeks
2+ weeks
Minimum Equity
30%
~27%
30%
Income Requirements
No
No
No
Minimum Home Value
$175,000
$140,000
$200,000
Number of States Covered
26
28 + DC
13
Fund Use Restrictions
No
No
No
Transaction Fee
4.90%
3.90%
4.99%

Best If You Want to Pay It Back Piece by Piece

Most of these companies want their money back in one shot, at the end. Unlock stands out because it lets you make partial payments along the way instead of waiting for a single big settlement. If the idea of owing one large number ten years from now makes you nervous, that flexibility is worth something. Unlock is also fairly loose on property type, it’ll work with second homes, rental units, and multi-unit buildings that some competitors won’t touch, and it doesn’t lean hard on credit score or income the way a traditional lender would.

Homeowners who like the idea of chipping away at the balance over time rather than facing one big payoff day, or anyone with a rental or second property that other providers won’t finance.

Best If You Want Maximum Breathing Room

Point gives you up to 30 years to settle up, which is a completely different animal than a ten-year clock. That kind of runway matters if you’re older, if you’re not sure when or if you’ll ever sell, or if you just don’t want a deadline hanging over you. Point is also one of the few that will work with investment properties and LLC-owned homes, which makes it a favorite among real estate investors. It’s been around since 2015, longer than most of its rivals, and it operates in a wide range of states.

Homeowners who want to set it and forget it, retirees who’d rather let the agreement resolve through their estate than worry about a hard deadline, and real estate investors.

Best If You Want Your Payoff Timed to Your Mortgage, Not a Fixed Calendar

Splitero’s signature feature is something it calls Maturity Match: instead of picking an arbitrary term length, your home equity agreement is timed to line up with however much is left on your actual mortgage. It also tends to work with lower credit scores than some competitors, doesn’t ask about income or employment at all, and moves quickly, often pre-approving within a day or two. The trade-off is that its fees can run a bit higher than the others, and it repays in one lump sum rather than letting you chip away at it.

Homeowners with less-than-perfect credit, self-employed or retired folks without traditional income to verify, and anyone who likes the idea of their equity agreement quietly ending whenever their mortgage does.

So Which One Is Actually "Best"?

Honestly? There isn’t one. That’s not a cop-out, it’s just how this product works. The right pick comes down to 4 questions:

  1. How long do you realistically need before you’ll settle up?
    1. Mortgage-matched term → Splitero.
    2. Longer runway → Point.
    3. Flexible payoff → Unlock.
  2. How’s your credit and income situation?
    1. Strong, traditional profile → you’ve got your pick.
    2. Thinner file, self-employed, or retired → Splitero or Unlock tend to be more forgiving.
  3. Do you want to pay it off gradually or all at once at the end?
    1. Gradually → Unlock.
    2. All at once, later → the others.
  4. Do you hate HEAs/HEIs?
    1. Just get a refinance.

One Last Thing, Seriously

One last thing worth keeping in mind: whichever company you’re leaning toward, remember what you’re actually doing; you’re not borrowing money, you’re sharing a piece of your home’s future growth with someone else. If your neighborhood really takes off in value over the next several years, that slice you gave up could end up being worth more than what a traditional loan would’ve cost you. That doesn’t make these products a bad deal, they’re genuinely useful, especially if you don’t want a new monthly payment or can’t easily qualify for one. It just means the real cost isn’t always obvious at first glance, so it pays to actually shop around. Get quotes from more than one company, since terms and offers can vary more than you’d expect. And before you sign anything, run the numbers on a few different scenarios and maybe loop in a financial advisor.

Unlock

Funding in 30-60 days

Unlock – Home Equity Agreement

NMLS ID #2657081

Access $15K to $500K from your home’s equity with flexibility and no monthly payments.

Point

Funding in 3 weeks

Point – Home Equity Agreement

NMLS ID #1610752

Receive up to $600k of your home equity, your way. Choose maximum flexibility.

Splitero

Funding in 2+ weeks

Splitero – Home Equity Investment

NMLS ID #2327455

Receive up to $500,000 of your home equity, without another monthly payment.

SavviestSaver.com is an independent, advertising-supported website. We may receive compensation from companies and partners featured on our website when users click on certain links, submit an application, or take other qualifying actions. This compensation may influence how and where offers are displayed, but it does not determine our editorial opinions or recommendations.

The information, opinions, reviews, and recommendations published on SavviestSaver.com are provided for general informational and educational purposes only. They are based on information available to us at the time of publication and do not constitute financial, legal, tax, or investment advice. Readers should independently evaluate any product or service and review its terms, conditions, fees, eligibility requirements, and risks before making a decision.

SavviestSaver.com does not provide, originate, or guarantee financial products or services. We are not responsible for the products, services, websites, content, offers, or practices of third-party companies. Any decision to apply for, enter into, or use a financial product or service is made solely by the consumer and the applicable provider.

Company names, product names, logos, and trademarks mentioned on this website belong to their respective owners. Their appearance on SavviestSaver.com does not necessarily imply an endorsement, partnership, affiliation, or sponsorship unless expressly stated.

We make reasonable efforts to keep the information on our website accurate and up to date. However, financial products, rates, terms, eligibility requirements, and other details may change. Information on SavviestSaver.com should not be relied upon as a substitute for reviewing information directly from the provider. We encourage readers to verify all relevant details with the company offering the product or service.

Home Equity Agreement Disclaimer

Home Equity Agreements (HEAs), and Home Equity Investments (HEIs), are not traditional loans and may have different terms, costs, and regulatory treatment depending on the provider and the state in which you live. An HEA generally involves receiving funds today in exchange for sharing a portion of the future value or appreciation of your home.

Because the agreement is secured by an interest in your home, certain events (such as selling the property, refinancing, or reaching the end of the agreement term) may trigger repayment or settlement obligations. Depending on the terms of the agreement and changes in your home’s value, the amount you ultimately owe or give up may be greater than the amount you initially received.

Before entering into an HEA or HEI, carefully review the complete agreement, including fees, settlement terms, valuation methods, repayment obligations, and any potential impact on your home. Consider consulting a qualified financial, legal, or tax professional to determine whether the product is appropriate for your individual circumstances.

SavviestSaver.com does not guarantee that any particular home equity product is suitable for your financial situation or that you will qualify for any offer discussed on this website.

One Response